

Together Loans analysis by Appwee
Managing a loan is rarely something I want to turn into a daily chore. I usually want a clear view of what I owe, an easy way to check the account, and a dependable place to handle routine loan tasks without searching through old messages or opening a browser. That is the space Together Loans aims to fill. It is a free finance app from Transform Credit Inc, built around managing a loan in one place rather than acting as a general-purpose banking replacement.
After looking at it as a practical loan-management tool, my view is fairly straightforward: Together Loans is most useful when you already have a loan connected to the service and want a focused mobile account. It is not the kind of finance app I would choose for budgeting, investing, comparing lenders, or watching every part of my household money. Its value comes from being narrow and direct, which is also the main reason some people may find it too limited.
What Together Loans is designed to do
The app sits in the finance category and is developed by Transform Credit Inc. Its purpose is reflected in the name: it gives borrowers a mobile place to manage their Together Loans account. That focus matters because many finance apps try to combine spending analysis, credit monitoring, savings tools, bill reminders, and account aggregation. This one is easier to understand. I would approach it as a companion for an existing loan, not as a complete personal-finance dashboard.
The app is free to install, and its content rating is Everyone. It is available for devices running Android 7.0 or later, which makes it accessible to people using older Android phones as well as newer models. The current Android version is 9.1.2. Those details make the basic entry decision simple: there is no purchase price for accessing the app itself, but free access should not be confused with the financial cost of borrowing. Any loan terms, repayment obligations, interest, fees, or eligibility decisions belong to the loan agreement rather than the download price.
That distinction is important when judging value. I would not describe Together Loans as a free loan, and I would not use the app’s free status as a reason to borrow. The app is free as a management tool. Its practical benefit is the convenience of handling an existing borrowing relationship from a phone.
Public response gives the app a 4.3 average from around 600 ratings, with more than 270 written reviews and over 100 thousand installs. I see that as a sign that the concept is useful to a meaningful group of borrowers, while still leaving room for individual experiences to differ. A rating can tell me that people generally find an app worthwhile, but it cannot replace checking whether its account tools fit my particular loan situation.
A focused account rather than a full banking app
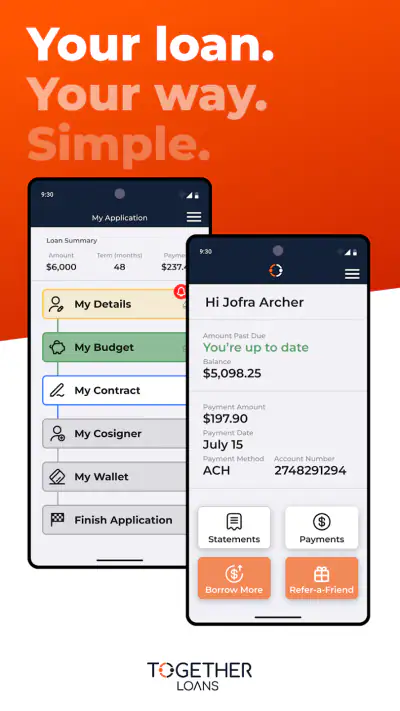
The first useful insight is that the app’s narrow purpose can reduce mental clutter. If I only need to review or manage a Together Loans account, a dedicated app may be quicker than navigating a lender website or opening a broad banking app that does not actually control the loan. The smaller scope can also make the app easier to explain to someone who is not comfortable with complicated financial software.
At the same time, I would not expect it to replace my bank’s mobile app. My bank remains the place I would use to monitor income, everyday spending, transfers, and savings. Together Loans is better understood as one account-management layer alongside those tools. That separation can be helpful, but it means I may still need another app or service to understand the effect of a repayment on my overall monthly budget.
How I would use it in everyday life
Imagine I have a repayment due while I am away from home and want to check the loan account before moving money between accounts. I could open Together Loans, review the relevant account information, and then use my regular banking app to make sure the money is available. That two-app workflow is not as seamless as a fully integrated bank account, but it is clearer than relying on memory or searching through email.
Another realistic use is checking the account after making a payment. I would want to confirm that the loan record reflects the latest activity before assuming everything is settled. A dedicated loan app gives me a natural place to perform that check. My advice would be to treat the app as a visibility and management aid, while keeping personal records of important payment dates and confirmations. Financial apps are convenient, but I would not rely on a single screen as my only record for a significant obligation.
The app may also be useful when preparing for a conversation with customer support. Before contacting the lender, I could review the account and note the exact issue I need to ask about. That preparation can make a support interaction more efficient. It is a small advantage, but one that matters when the problem involves a repayment, account detail, or timing question.
Where the free price offers real value
Because the app itself is free, the value question is mainly about time, access, and clarity. If it saves me from repeatedly signing in through a mobile browser, remembering a web address, or hunting for loan information among unrelated accounts, the convenience is meaningful. A free dedicated tool can be worthwhile even when it does not offer sophisticated financial analysis.
I also like the fact that the download decision is relatively low-risk from a purchase standpoint. I am not paying upfront for a premium dashboard, a subscription, or an upgrade simply to see whether the account-management experience suits me. That makes it reasonable for an existing borrower to try the official app and decide whether it is more comfortable than the usual browser route.
Still, I would judge the app by how reliably it helps me complete ordinary loan tasks, not by the absence of a price tag. A free app that makes me repeat steps, leaves account information unclear, or does not fit my loan arrangement would have little practical value. Free access removes a financial barrier to trying it; it does not guarantee that it is the best way to manage the account.
Practical tradeoffs before relying on it
The narrow scope can be a strength and a weakness
Together Loans is appealing precisely because it concentrates on one relationship. The tradeoff is that I would need another tool for almost every question outside that relationship. If I want to know whether a repayment fits comfortably alongside rent, utilities, credit-card balances, and savings goals, this app alone will not give me the complete picture. I would need to combine it with my bank’s tools or a separate budgeting method.
That means the app is not ideal for someone looking for a single finance command center. A broader budgeting app may be better for comparing monthly obligations across several lenders. A bank app may be better for moving money and tracking spending. A web browser may remain preferable for someone who manages several financial products on a desktop and wants everything in one session.
Mobile convenience does not remove the need for careful checking
A loan account deserves more attention than a casual shopping app. Before acting on any displayed information, I would check that I am viewing the correct account and that the details match my own records. If I were making a payment or responding to an account issue, I would review the amount and timing carefully rather than tapping through quickly because the app feels convenient.
This is one of the less obvious tradeoffs of a dedicated mobile tool: speed can encourage overconfidence. A clean account screen may make a financial decision feel simpler than it really is. I would use the app to access information and manage routine tasks, but I would read the loan agreement for the rules that actually govern repayment. The app should support good decisions, not replace them.
Older Android support is useful, but device experience can vary
Support for Android 7.0 or later is helpful for people who have not upgraded recently. It also means the app is not restricted to only the newest phones. However, older devices can differ in screen size, performance, security updates, and notification behavior. I would keep the phone’s operating system updated where possible and make sure I can still access the account through an alternative route if the device becomes unreliable.
This is not a criticism unique to Together Loans; it is a sensible precaution for any app connected to borrowing. A phone can be lost, replaced, or temporarily unavailable. I would not let the app become my only way to understand an important loan. Keeping key account information and support details safely available elsewhere is a practical backup.
What I would check during the first setup
My first session would be deliberately slow. I would confirm that the app is the official Together Loans application associated with Transform Credit Inc, sign in using the account details I normally use for the loan, and inspect the account screen before attempting any transaction. I would also look for the places where account status, payment information, and support access are presented, so I know where to return later.
After that, I would compare one visible account detail with my existing loan paperwork or previous records. This is a simple but valuable habit: it confirms that I am in the right account and helps me understand how the app presents the information. I would avoid judging the entire app from the sign-in screen alone. The real test is whether I can find the information I need without confusion when I am under time pressure.
A second useful habit is to check the app after a routine account change and note how quickly the record becomes understandable. I would not assume that an action is complete merely because I submitted it. I would look for a clear status or confirmation, save any important reference information, and verify the account again later if the matter is time-sensitive. That workflow is more cautious than simply trusting a button press, but it is appropriate for loan management.
Who will get the most value
I think Together Loans is best for an existing borrower who wants a dedicated Android account tool and prefers using a phone to a mobile browser. It should also suit someone who finds broad finance apps distracting and wants loan information kept separate from everyday spending. The free download makes it easy to try without committing to a paid finance service.
It may be particularly helpful for people who check their loan periodically rather than constantly. The app does not need to become part of a daily routine to be useful. Opening it before a planned payment, after an account update, or when preparing a support question may be enough to justify keeping it installed.
I would be more cautious about recommending it to someone who has several loans and wants one combined payoff plan. That person may benefit more from a budgeting spreadsheet, a general finance app, or a bank tool that shows all obligations together. I would also point a person toward a browser or desktop workflow if they strongly prefer larger screens, printed records, or managing multiple financial documents side by side.
Questions I would answer before installing
The first question is whether the app costs anything to download. It is free, so there is no app purchase to budget for. The important qualification is that the loan itself remains governed by its own terms; downloading the app does not change the cost of borrowing.
The second question is whether it is meant for everyone with any kind of loan. I would not assume that. Its purpose is to manage Together Loans, so the sensible reason to install it is having a relevant loan account or being directed to use the service’s account-management app. It is not a general lender marketplace or a universal loan tracker.
The third question is whether it can replace a banking app. In my view, no. I would use it for the Together Loans relationship and keep my bank app for balances, transfers, and spending. If I need a complete household budget, I would add a separate method rather than expecting this focused app to provide it.
The fourth question is whether an older Android phone can run it. Android 7.0 is the minimum operating system, so many older devices remain eligible. I would still consider the phone’s security and performance, especially because financial account access deserves a device that receives dependable updates.
The final question is whether the app is worth keeping if I rarely check my loan. I think it depends on the alternative. If the app gives me faster access than the website and helps me verify account activity, it can be useful even for occasional visits. If I already have a reliable browser routine and prefer not to install dedicated finance apps, the benefit may be too small to matter.
My buy-or-skip verdict
I would recommend trying Together Loans if I already had a Together Loans account and wanted a free, focused way to manage it from an Android phone. The app’s strongest quality is not breadth; it is the straightforward idea of keeping loan access in a dedicated place. The rating and install base suggest that many borrowers find that approach worthwhile, although I would still judge the experience against my own account needs.
I would skip it if I were searching for budgeting, loan comparison, credit education, investment tracking, or a complete replacement for mobile banking. Those jobs call for different tools. I would also skip relying on it as my only financial record, because a loan is too important to manage without basic personal backups and careful attention to the underlying agreement.
My final assessment is positive but deliberately limited: the free access makes Together Loans easy to test, while its focused purpose determines whether it is genuinely valuable. For the right borrower, it can turn occasional loan administration into a simpler phone-based routine. For everyone else, especially people seeking an all-in-one finance manager, its narrow design is a reason to look elsewhere rather than a flaw to overlook.
Gallery
Together Loans Pros and Cons
- Simple way to explore shared borrowing options in one place.
- May help users compare loan offers without visiting multiple lenders.
- Useful for borrowers who prefer managing applications from a mobile device.
- Can provide access to financing options for different credit profiles.
- Digital application process may save time compared with traditional paperwork.
- Approval
- rates
- and terms depend on the participating lender.
- Loan offers may include origination fees or other additional costs.
- Not all applicants will qualify for the available financing options.
- Sharing financial information requires careful review of privacy policies.
- Repayment amounts can become expensive if the loan term is extended.
Together Loans Frequently Asked Questions
What is Together Loans, and how does the application work?
Together Loans is a loan-related service designed to help users explore borrowing options and manage the application process through a digital platform. Depending on your location and eligibility, you may be able to submit personal and financial information, review available loan products, and receive communication about your request. The app or website does not necessarily guarantee approval, and final terms are determined after the provider completes its assessment.
Who can apply for a loan through Together Loans?
Eligibility depends on factors such as your age, country or region, income, employment status, credit history, and ability to repay. Together Loans may also require applicants to provide valid identification, contact details, bank information, and other supporting documents. Meeting the basic requirements does not ensure approval, because lenders can apply additional criteria and may decline an application after reviewing the submitted information.
Are Together Loans free to use, and what costs should I check?
Using a loan-matching or application service may be free, but the loan itself can include interest, arrangement charges, late-payment fees, broker fees, or other costs. Before accepting any offer, carefully review the annual percentage rate, repayment schedule, total amount repayable, and consequences of missed payments. Never rely only on the advertised rate, since your personal offer may be different.
Will applying through Together Loans affect my credit score?
The effect on your credit file depends on how Together Loans and its lending partners process your request. An initial eligibility check may use a soft search that does not affect your score, while a formal application can involve a hard credit inquiry. Read the privacy and credit-check explanations carefully before submitting your details, particularly if you plan to apply with several providers.
Is Together Loans safe, and what should I consider before downloading or applying?
Before using Together Loans, verify that the service is officially available in your country and that the company and any lending partners are properly authorized where required. Download the app only from a trusted store, check its privacy policy and permissions, and avoid sharing sensitive information through unofficial links. Also compare alternative lenders, confirm the full repayment cost, and borrow only an amount you can realistically repay.














